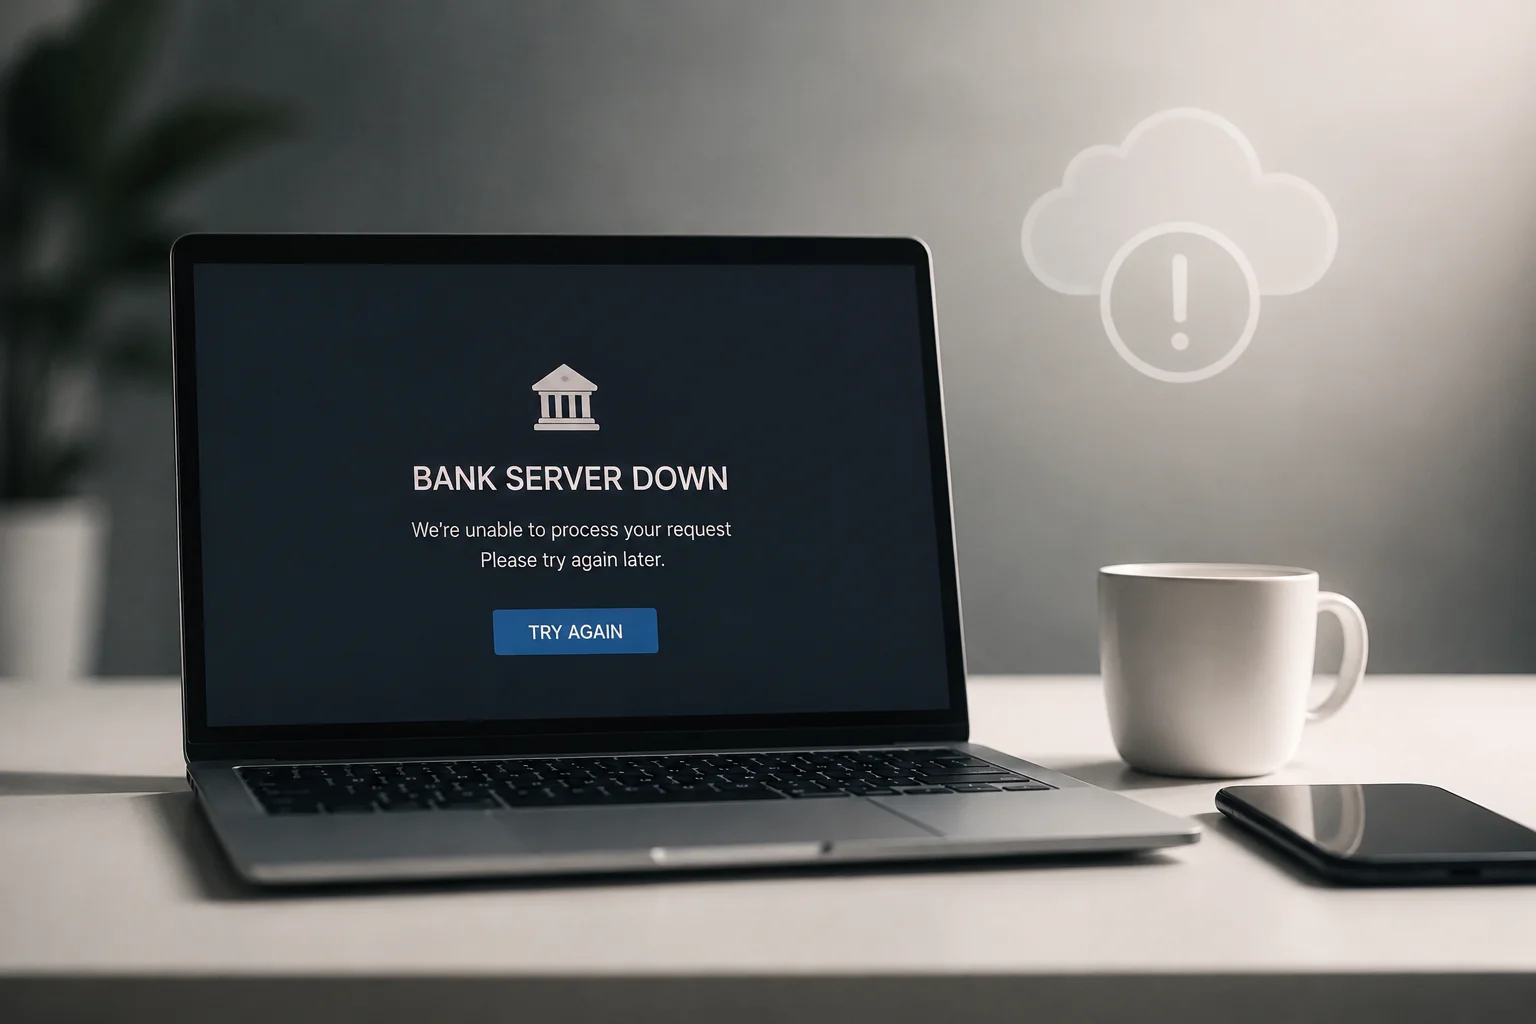
In today’s digital banking era, people expect banking services to work instantly and continuously. Whether it’s transferring money, checking balances, making card payments, or using mobile banking apps, modern consumers rarely think about the complex infrastructure operating behind the scenes.
But every now and then, headlines appear about a banking outage. Customers suddenly cannot log in. Transactions fail. ATMs stop responding. Card payments decline. Mobile apps freeze. Social media fills with frustrated users asking the same question:
What Happens when a Bank Server goes Down?
Behind the scenes, things are much more complex than they appear. A banking outage is not simply “a server crash.” Modern banking systems operate through highly interconnected networks involving core banking infrastructure, payment gateways, cloud systems, fraud monitoring engines, APIs, settlement networks, and data replication systems.
When one critical component fails, the impact can ripple across the entire financial ecosystem.
The Difference Between a Server Failure and a Banking Outage
Most people assume banks operate on a single server or centralized system. In reality, large banking institutions rely on massive distributed infrastructures spread across multiple data centers and cloud regions.
A single “bank server” may actually refer to:
- Authentication servers
- Transaction processing servers
- Database clusters
- Payment gateway systems
- ATM switching systems
- Mobile banking APIs
- Fraud detection engines
- Card authorization systems
- Internal reconciliation platforms
Sometimes a failure affects only one service. Other times, a deeper infrastructure issue can disrupt multiple banking channels simultaneously.
This is why users may still access ATMs while mobile banking fails, or why online transfers stop working while card payments continue normally.
What Happens the Moment a Banking System Fails
The first few seconds after a critical failure are extremely important.
Modern banks use automated monitoring systems that continuously track:
- Server health
- CPU usage
- Database latency
- Network congestion
- Transaction queues
- API response times
- Authentication failures
The moment abnormal behavior appears, monitoring systems generate alerts for engineering and operations teams.
In severe outages, banks may immediately trigger automated failover mechanisms.
This means traffic is redirected to backup systems or secondary data centers designed specifically for disaster recovery situations.
However, failovers are not always seamless.
If databases are not perfectly synchronized or if network dependencies break during migration, customers may experience delays, failed transactions, or temporary service restrictions.
Why Transactions Sometimes “Disappear”
One of the biggest fears during a banking outage is missing money.
A customer may see:
- Money debited but not received
- Failed transfers with pending deductions
- Duplicate payment notifications
- Delayed balance updates
In most cases, the money is not actually lost.
Modern banking systems process transactions through multiple stages:
- Authorization
- Processing
- Clearing
- Settlement
- Reconciliation
If a server outage interrupts communication between these layers, the transaction may remain stuck in an intermediate state.
Banks usually maintain transaction logs and recovery queues that help restore pending operations once systems stabilize.
This is why some transactions appear reversed hours later.
The Role of Redundant Infrastructure
Banks spend billions building redundancy systems because downtime directly impacts trust and financial stability.
Most major financial institutions operate:
- Multiple backup servers
- Replicated databases
- Geographic failover centers
- Real-time data synchronization
- Disaster recovery environments
- Load balancing systems
The goal is simple:
No single hardware failure should bring down the entire banking operation.
However, real-world outages often involve more than hardware failure.
Common causes include:
- Software deployment errors
- Database corruption
- Cloud service outages
- API failures
- Network routing problems
- Cybersecurity incidents
- Human operational mistakes
- Third-party payment network failures
In many modern banking outages, the root cause is software complexity rather than physical server damage.
Why Mobile Banking Apps Fail First
During outages, mobile banking apps are usually the first visible casualty.
This happens because apps rely heavily on real-time APIs connected to backend banking infrastructure.
If authentication services slow down or API gateways become overloaded, the mobile app cannot retrieve account information properly.
Interestingly, the core banking system itself may still be operational internally while customer-facing channels fail externally.
A lot of what makes inside a bank server failure: what happens when banking systems go offline interesting only shows up once you spend real time with it. This overlaps quite a bit with transaction, a subject thesindi.com looks at from a few angles. It adds some useful context either way.
This distinction is important because banks often prioritize protecting transaction integrity over maintaining app availability.
In other words, temporarily blocking access is safer than risking inconsistent financial records.
The Growing Complexity of Modern Banking Infrastructure
Today’s digital banks operate more like technology companies than traditional financial institutions.
Modern banking platforms depend on:
- Cloud computing environments
- Microservices architecture
- Third-party integrations
- Open banking APIs
- Real-time fraud analytics
- AI-based transaction monitoring
- Distributed databases
As a result, even small technical issues can cascade into larger operational failures.
For example, a slow authentication system may overload login servers, which then increases API latency, eventually affecting transaction systems and customer access simultaneously.
This interconnected structure makes banking resilience both highly advanced and extremely fragile.
Platforms such as https://secure-tangerine.ca/ represent how digital-first banking ecosystems increasingly depend on secure online infrastructure, high uptime reliability, and scalable backend systems to maintain uninterrupted financial services for users.
What Happens Behind the Scenes During Recovery
Once the immediate crisis is contained, recovery teams begin a much larger process.
This includes:
Transaction Verification
Banks verify incomplete or queued transactions to ensure financial consistency.
Database Integrity Checks
Engineers validate whether replicated databases stayed synchronized during the outage.
Fraud Risk Analysis
Outages can create opportunities for fraudulent behavior, so unusual transaction patterns are closely monitored afterward.
Service Prioritization
Critical systems are restored first, such as:
- Card authorization
- ATM functionality
- Interbank transfers
- Customer authentication
Less essential features may remain offline longer.
Regulatory Reporting
Major outages often require reporting to financial regulators depending on jurisdiction and severity.
Why Banking Downtime Creates Massive Financial Pressure
For banks, downtime is not just a technical problem.
It creates:
- Customer trust issues
- Reputational damage
- Operational disruption
- Compliance concerns
- Financial liability
- Increased support costs
Even short outages can affect millions of transactions globally.
Large institutions may process thousands of operations every second, meaning a 30-minute disruption can create enormous transaction backlogs.
This is why banks heavily invest in resilience engineering, high-availability systems, and cyber recovery infrastructure.
Can Banking Systems Ever Become 100% Reliable?
No banking infrastructure is completely immune to failure.
Even the world’s largest financial institutions occasionally experience outages because modern banking systems are incredibly complex.
What matters most is:
- Recovery speed
- Transaction integrity
- Data consistency
- Customer communication
- Disaster recovery planning
The future of banking resilience will likely depend on:
- AI-powered monitoring
- Predictive infrastructure analytics
- Advanced cloud redundancy
- Distributed transaction architecture
- Real-time failover automation
Banks are moving toward systems designed not merely to prevent outages, but to survive failures without disrupting customers significantly.
Final Thoughts
When a bank server goes down, the problem extends far beyond a simple technical malfunction. Modern banking systems are deeply interconnected digital ecosystems where one infrastructure failure can affect authentication, payments, transfers, balances, and customer access simultaneously.
Behind every banking outage is a large-scale operational response involving engineers, cybersecurity teams, transaction specialists, compliance officers, and recovery systems working together to restore stability.
For users, the outage may appear as a frozen banking app or failed payment.
Behind the scenes, however, banks are managing one of the most technically demanding environments in the modern digital economy.
I love it when people come together and share opinions, great blog, keep it up.