
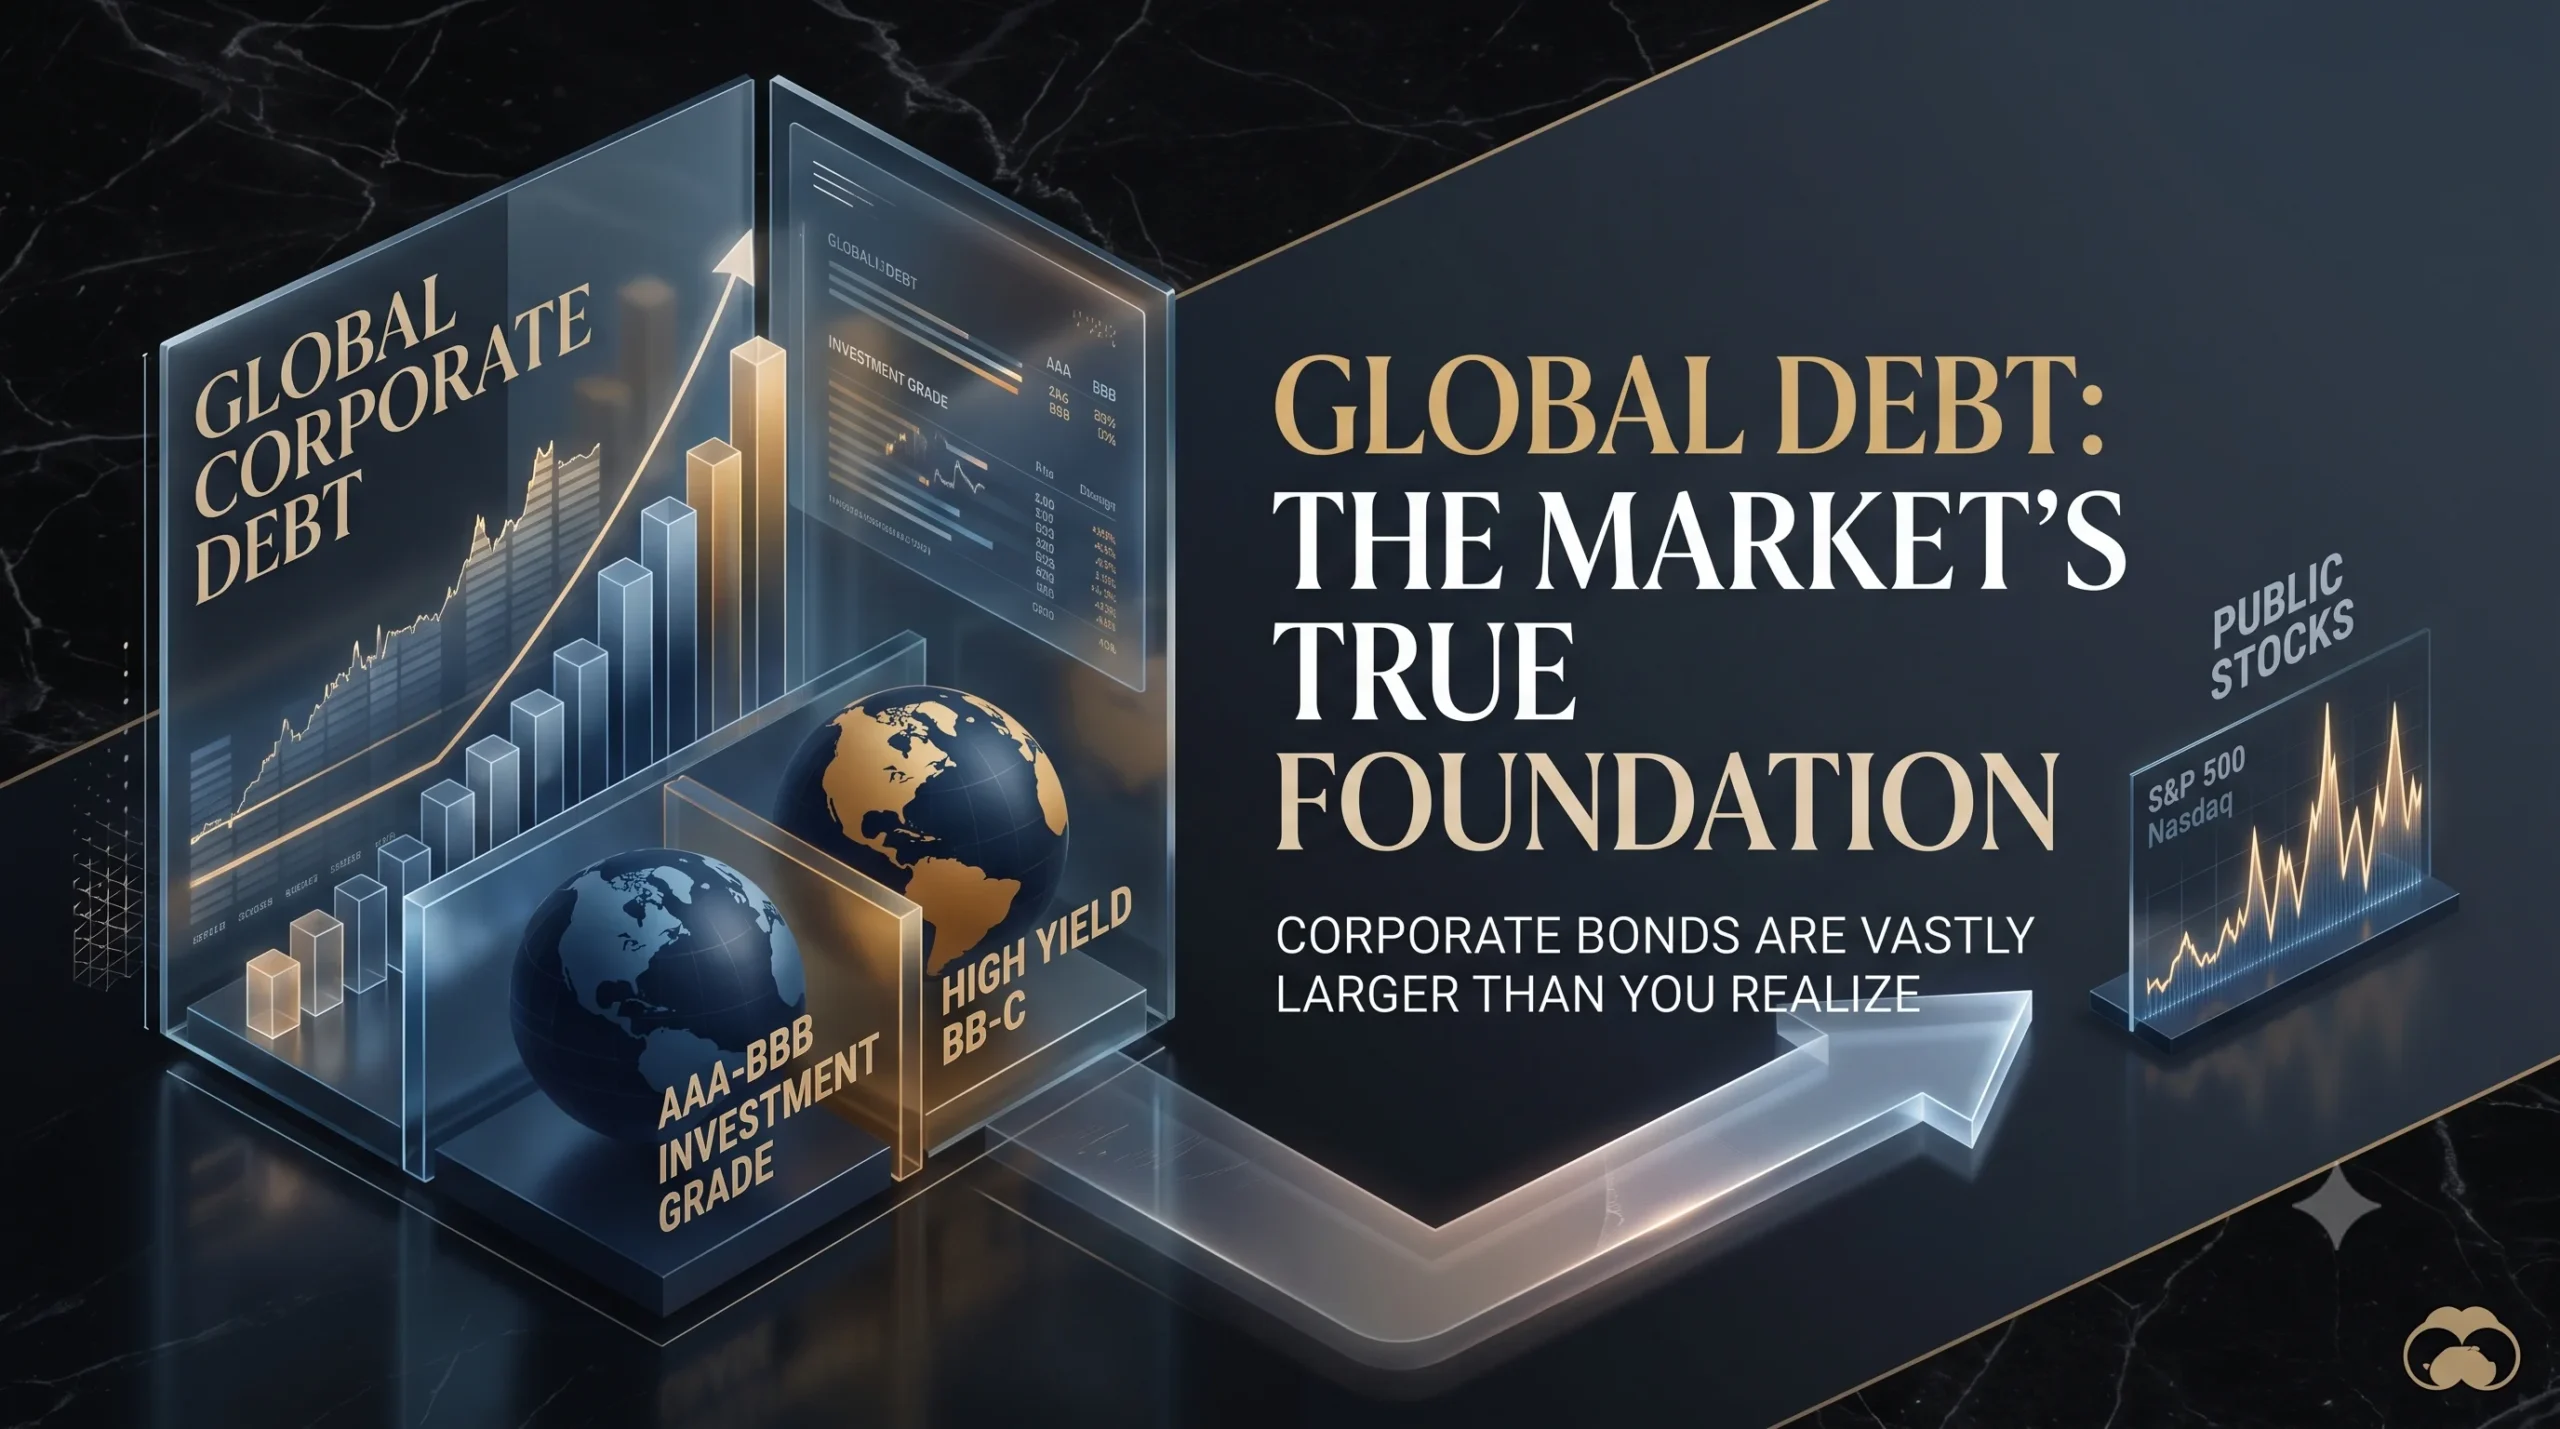
When financial news networks broadcast daily market updates, the focus falls almost exclusively on stock indices: the S&P 500, the Nasdaq, the FTSE 100, or individual corporate stock charts. This equity-centric bias creates a widespread illusion among retail investors—the belief that the stock market is the primary engine of global capital allocation.
In reality, the global corporate bond market is vastly larger, more liquid, and far more influential in dictating macroeconomic health.
While equities capture the cultural imagination because of high-profile IPOs and volatile share price swings, the global fixed-income universe—specifically corporate debt—serves as the true financial foundation for major corporations, sovereign nations, and institutional pension funds.
1. The Sheer Scale: Stocks vs. Corporate Bonds
To understand the magnitude of the corporate bond market, one must look at total capital outstanding rather than daily media headlines.
Global equity markets account for roughly $110 trillion to $120 trillion in market capitalization. However, total global debt outstanding frequently surpasses $300 trillion, with corporate debt (excluding sovereign and municipal bonds) representing a massive segment of that total—exceeding $50 trillion globally.
Global Financial Asset Breakdown (Approximate Trillions USD)
┌─────────────────────────────────────────────────────────────┐
│ Sovereign & Government Debt (~$90T - $100T)                │
├─────────────────────────────────────────────────────────────┤
│ Global Corporate Debt (~$50T - $60T)                       │
├─────────────────────────────────────────────────────────────┤
│ Global Equity Market Cap (~$110T - $120T)                  │
└─────────────────────────────────────────────────────────────┘
For major multinational conglomerates, outstanding debt regularly dwarf their annual equity turnover. Companies like Apple, Microsoft, Amazon, and Toyota maintain tens of billions of dollars in outstanding corporate bonds even when sitting on significant cash balances.
2. Why Corporations Choose Debt Over Equity
A fundamental question arises: why do healthy, highly profitable corporations issue debt instead of simply issuing more equity or using accumulated cash reserves?
The answer lies in corporate finance theory, specifically the optimization of the Weighted Average Cost of Capital (WACC).
                  WACC Optimization Equation
 ┌──────────────────────────────────────────────────────────┐
 │  WACC = (E/V × Cost of Equity) + (D/V × Cost of Debt)  │
 └──────────────────────────────────────────────────────────┘
The Tax Shield Advantage
In almost every major economic jurisdiction, interest paid on corporate debt is treated as a tax-deductible operating expense. Dividends paid to equity shareholders, by contrast, are paid out of after-tax profits.
This creates a structural financial advantage known as the interest tax shield:
Debt Financing:   Revenue ──► Interest Expense (Tax Deductible) ──► Lower Taxable Income
Equity Financing: Revenue ──► Taxable Income ──► Income Tax Paid ──► Dividend (No Tax Shield)
Because of this tax treatment, borrowing money is mathematically cheaper for a corporation than issuing equity, even before accounting for investor return expectations.
Non-Dilutive Capital Structure
When a company issues new equity, it dilutes existing shareholders’ ownership percentages and claims on future earnings. Issuing a corporate bond allows management to raise billions of dollars for capital expenditures, R&D, or strategic acquisitions without surrendering a single share of equity control.
3. Market Structure: How Corporate Bonds Actually Trade
Unlike stock markets—which trade on centralized, highly transparent public exchanges like the NYSE or Nasdaq—the corporate bond market operates predominantly as an Over-the-Counter (OTC) dealer network.
Stock Market Model:        Buyer ──► Centralized Exchange (NYSE/Nasdaq) ──► Seller
Corporate Bond OTC Model:  Buyer ──► Primary Dealer Bank Network        ──► Institutional Seller
The Institutional OTC Landscape
Corporate bond trades do not occur in micro-second retail matching engines. Instead, large institutional players—such as investment banks, sovereign wealth funds, insurance companies, and bond funds—negotiate multi-million-dollar transactions directly via dealer networks.
Because transactions occur OTC, price discovery relies on yield spreads benchmarked against government risk-free rates (such as US Treasuries).
| Feature | Public Stock Markets | Corporate Bond Markets |
| Trading Venue | Centralized Exchanges | Over-the-Counter (OTC) Dealer Networks |
| Primary Investors | Retail + Institutional | Overwhelmingly Institutional (90%+) |
| Pricing Metric | Price Per Share ($ USD) | Yield to Maturity (YTM) & Spread (bps) |
| Maturity Structure | Perpetual (No Expiration) | Fixed Maturity Dates (1 to 30+ Years) |
| Capital Stack Priority | Lowest Priority (Residual Claim) | Senior Priority (Secured or Unsecured) |
Comprehensive financial coverage on thesindi.com .
highlights how institutional investors analyze these yield spreads across economic cycles to anticipate corporate default risks long before they surface in stock valuations.
4. The Risk Spectrum: Investment Grade vs. High Yield
The corporate bond market is broadly bifurcated into two distinct risk categories based on credit ratings issued by agencies like Moody’s, S&P, and Fitch:
Investment Grade (IG)
- Credit Ratings: AAA down to BBB- (or Baa3).
- Profile: Issued by blue-chip, financially sound corporations with minimal default risk.
- Yield Characteristics: Lower interest rates, closely tracking government benchmark yields plus a narrow credit spread (e.g., 50 to 150 basis points).
- Primary Buyers: Pension funds and life insurance companies seeking guaranteed cash flows to match long-term liabilities.
High-Yield (“Junk”) Bonds
- Credit Ratings: BB+ (or Ba1) down to C/D.
- Profile: Issued by leverage-heavy, higher-risk, or fast-growing companies.
- Yield Characteristics: Significantly higher interest rates to compensate for default risk, trading at wide spreads above risk-free rates.
- Primary Buyers: High-yield bond funds, hedge funds, and private credit managers seeking capital appreciation alongside income.
5. The Continuum of Corporate Debt: From Public Markets to Private Credit
While public corporate bond markets provide liquidity for established enterprise conglomerates, a massive ecosystem of alternative debt financing operates just beneath the public surface.
Over the past decade, regulatory tightening on traditional banks has pushed corporate borrowing toward private credit markets. Middle-market companies and venture-backed technology firms that cannot access public bond markets rely on private lenders, direct debt funds, and specialized credit structures to fund their growth.
This creates a continuous capital ladder: early-stage companies leverage specialized non-dilutive loan structures—as detailed in our analysis of how Venture Debt Has Become the Startup Funding Nobody Talks About .
—before eventually maturing into private direct lending, high-yield issuance, and ultimately investment-grade public bond markets.
                    THE CORPORATE DEBT CAPITAL LADDER

   ┌────────────────────────────────────────────────────────────────┐
   │ 4. Public Investment-Grade Bonds (AAA to BBB-)                 │
   │    Blue-chip multinationals, lowest yield, massive volume       │
   ├────────────────────────────────────────────────────────────────┤
   │ 3. Public High-Yield / Junk Bonds (BB+ to C)                   │
   │    Leveraged enterprises, higher yields, institutional liquidity │
   ├────────────────────────────────────────────────────────────────┤
   │ 2. Middle-Market Private Credit & Direct Lending               │
   │    Bespoke institutional loans, direct debt funds              │
   ├────────────────────────────────────────────────────────────────┤
   │ 1. Venture Debt & Alternative Startup Credit                   │
   │    Early-stage, high-growth, non-dilutive venture-backed credit │
   └────────────────────────────────────────────────────────────────┘
Why Investors Must Pay Attention to Corporate Bonds
Even for equity-focused investors, understanding the corporate bond market is essential.
Bond markets are historically far better at pricing macroeconomic risk than stock markets. Credit investors sit higher in the capital stack and are hyper-focused on downside protection, balance sheet health, and debt coverage ratios.
When corporate bond yields spike or credit spreads widen, it signals that sophisticated institutional capital is pricing in credit stress. Equity markets often lag bond market warnings by months—making corporate debt the ultimate leading indicator for global financial markets.

One thought on “Corporate Bond Markets Are Bigger Than Most Investors Realize”
Comments are closed.